
Multi-Member LLC That Issues Invoices
Table Of Contents
A simpler way to accomplish the same thing as above is to create three entities again, but the multi-member LLC is owned by you (the humans) and the other guys, not the S corporations. Wait! What? While we showed the previous schematic, the following is the preferred arrangement. Why do we prefer it?
- State footprint. A K-1 from the mothership to your S Corp drags the mothership’s state income and apportionment into your S Corp. More on that in a bit. And it’s not good otherwise.
- California flexibility. Because humans own the mothership, it can elect S Corp status, which matters in California. An S Corp cannot have a corporation as a shareholder, so a mothership owned by S Corps never can. The tradeoff is that the mothership then follows S Corp rules, including the single class of stock restriction, so the fee for service agreements become even more important.
- No trapped appreciation. The baby S Corp doesn’t own an appreciating partnership interest, so you avoid the tax problem of getting that interest out of the corporation later. Liquidating an S Corp generally triggers gain on appreciated assets as if they were sold at fair market value, even when you simply distribute them to yourself (IRC Section 336). Revoke the S election instead, and you are left with a C Corp holding those assets, which is its own headache. This is also why we generally discourage holding rental real estate inside an S Corp.
- Cleaner basis at death. Your heirs generally receive a stepped-up basis in the mothership partnership interest, and an IRC Section 754 election can provide a corresponding inside basis adjustment. With S Corp ownership, the step-up generally stops at the corporate stock.
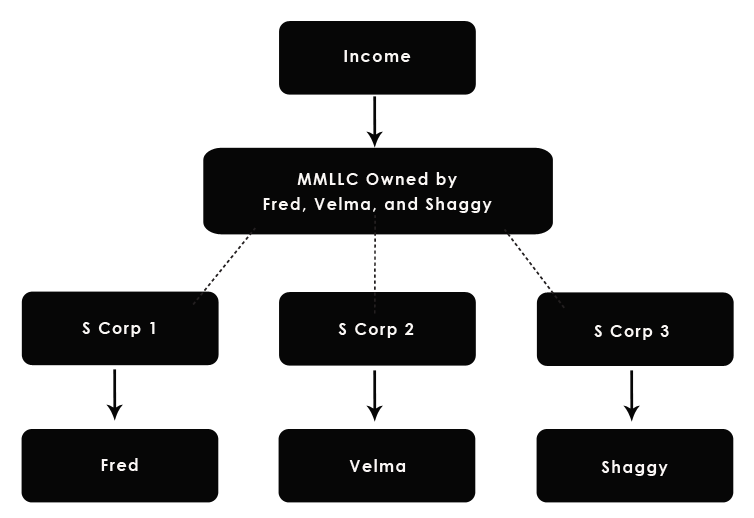 The baby S Corps issue consulting, fee for service or management invoices to the multi-member LLC under written services agreements. We typically recommend a recurring monthly service fee, supplemented by quarterly or annual performance fee bonuses or award fees based on production or another agreed formula. These fees can drive the MMLLC’s net business income after expenses down to zero or some nominal amount, such as $500, while directing the economics to each baby S Corp.
The arrangement needs real services, corporate control and commercially supportable compensation, but there is nothing inherently wrong with performance-based fees (see dotted lines below).
Therefore, each human receives two K-1s, a small one from the MMLLC or “mothership” and another from their respective S Corp. This still accomplishes the Eat What You Kill income splitting objective and changes the color of money through distributions from each person’s “baby” S Corp. Flexibility plus tax efficiency. Brilliant!
This would also be beneficial if you didn’t have an Operating Agreement, or if you are afraid that an Operating Agreement could be too restrictive from year to year. You would still need some sort of instrument or agreement that dictates how the fees are calculated so there aren’t any hard feelings.
What holds this up is the economic substance, backed by the paper. Income is taxed to whoever earns it (Lucas v. Earl, 281 U.S. 111 (1930)), and when an individual and a corporation both claim to be the earner, the Tax Court asks whether the corporation really controls the earning (Johnson v. Commissioner, 78 T.C. 882 (1982)). As such, you need-
- An employment agreement between you and your baby S Corp.
- A services agreement between the mothership and each S Corp, naming the S Corp as the provider and you as its employee.
- The S Corp named on outside contracts where your industry allows it.
- Your role at the mothership kept to governance.
With the proper agreements, real corporate control and commercially supportable fees, the arrangement becomes considerably more defensible. The contracts alone don’t do the work.
Regulated Industries
The above schematic is also preferred for regulated industries like financial advisors or real estate agents, where entity ownership must be held by individuals. In some states and with certain regulatory agencies, the MMLLC may be owned by S corporations provided the named principals are the licensed or regulated individuals… again, this arrangement avoids that issue.
Having said that, the baby S Corps typically must register separately with their regulatory body. For example, if you are a band of attorneys wanting the mothership baby S Corp multi-entity construct (yeah, we just made that up) with fee for service agreements, each S Corp would probably need to be registered as a law office with the state bar. This is a minor housekeeping detail, but an important one.
Financial advisors get extra homework. In Fleischer v. Commissioner, T.C. Memo. 2016-238, the broker-dealer contracts were in the advisor’s own name, so the Tax Court taxed the income to him rather than his S Corp. FINRA Rule 2040 generally prevents commissions from being paid to an unregistered entity, so the fix is getting your S Corp onto the contract, or forming a registered investment advisor (RIA) that elects S Corp status so the entity is the party. Whatever the industry, the baby S Corp must be the one earning the fee on paper.
State Income Tax Footprint
Another reason we prefer the fee for service arrangement, the mothership baby S Corp construct, is state income tax apportionment. Suppose your Illinois S Corp owns an interest in a California MMLLC. The partnership issues your S Corp a K-1, and here is the problem. California does not treat that K-1 income as sales or revenue your S Corp earned. It treats it more like income from an investment than revenue from your own customers, already sourced to California using the partnership’s numbers rather than your S Corp’s (Cal. Code Regs. tit. 18, 25137-1). Therefore, your S Corp cannot spread that income across its own customer locations the way it would its own revenue. If the partnership does most of its business in California, most of your K-1 is California income, period. Your S Corp can inherit a California tax reporting problem, and a California tax bill, simply by owning part of the partnership.
Now change the arrangement. You personally own the California MMLLC interest, while your Illinois S Corp provides services to the MMLLC under a business-to-business agreement. Instead of receiving partnership K-1 income, your S Corp earns service revenue. That revenue is sales, reported and apportioned based on the S Corp’s own business activities and the applicable state sourcing rules.
This gives you considerably more control over how the business relationship is structured and how the income is properly reported. California might still claim some of the service revenue, especially when the customer receives the benefit in California, but that is a different and usually friendlier analysis than receiving a California partnership K-1.
We are not suggesting you can simply pick whichever state gets the income. The point is that legitimate business structure and service agreements affect the tax reporting obligations. And given California’s enthusiasm for collecting taxes, that distinction is worth understanding.
Can the Mothership Accrue the Year-End Performance Fee?
Here is where the performance fee gets interesting, and where the tax pros reading along should pay attention. The final fee usually can’t be calculated until the books close in January. Can the mothership still deduct it in the year the services were performed? Yes, if the setup is right.
First, the mothership needs to be on the accrual method, since a cash-basis entity cannot simply accrue one favorite expense (Treas. Reg. 1.446-1(c)(1)(iv)). An accrued expense is deductible once the liability is fixed, the amount is reasonably determinable and economic performance has occurred (IRC Section 461(h)). In practice-
- The fee formula is established in a written agreement before year-end, with no remaining discretion to cancel the obligation.
- The baby S Corps performed the services during the year.
- The mothership records the expense and payable at year-end, even though the final calculation and cash payment happen in January.
Second, the other side must match. Each baby S Corp generally needs to report the fee as income for the same tax year, which usually means using the accrual method too. The related-party rules under IRC Section 267 can prevent the mothership from deducting a fee before the baby S Corp recognizes the income.
Third, a trap that catches tax pros. The baby S Corp generally cannot deduct an unpaid year-end bonus accrued to its cash-basis shareholder-employee, since even a minority S Corp shareholder is a related party under IRC Section 267(e). So when a large performance fee lands at year-end that the baby S Corp didn’t see coming, the extra profit flows through on the K-1. Two problems follow. The owner’s salary for the year might now look thin against a much bigger profit, which is a reasonable compensation problem. And the estimated tax payments and withholding were built on the smaller number, which can create an underpayment penalty problem.
The fix is watching the fee formula during the year, not after it. Quarterly performance fees help, and so does a December payroll true-up, additional year-end withholding (which counts as paid evenly throughout the year per IRC Section 6654(g)) or a timely fourth-quarter estimated payment.
Do I Issue a 1099 to My Own S Corp?
Generally, no. A 1099 is generally required only for payments to non-corporations. Even though you created an LLC and later elected S Corp status, you are now considered a corporation for information reporting, and your vendors are not required to send you a 1099 (although many do). Two common exceptions land squarely on this audience. Attorney fees and medical and health care payments are reportable regardless of corporate status, so a law practice mothership or a physician group mothership might still need to file them.
Here is a brief recap of the three ways cash can leave a mothership, covering both versions (the mothership owned by S Corps and the mothership owned by the humans)-
| Method | How It Works | Which Version | Watch |
| Distributions Under the Operating Agreement | The partnership allocates income on K-1s and distributes cash under the agreement | Either version | Income allocations and cash distributions are distinct; allocations must satisfy IRC Section 704(b) |
| Guaranteed Payments | Payments to the actual partners for services or capital, determined without regard to partnership income | Either version | Individual partners generally have self-employment income; S Corp partners are treated differently |
| Fees for Services | The mothership pays each baby S Corp under a business-to-business services agreement | Mothership owned by the humans (our preference) | Real services, corporate control, commercially supportable fees and proper accrual timing |
There are two additional considerations for the mothership baby S Corp construct (although we love the heck out of it)-
- In California, you might want the mothership to be taxed as an S corporation to avoid the California LLC fee based on total income. See our California Multi-Member LLC S Corp Twist section for more information.
- It might be better for the mothership to be a C corporation rather than an LLC. There is a line of authority asking whether a member paid for services within the LLC’s own business is really receiving a fee, or a share of partnership profit in disguise (IRC Section 707). A C Corp removes the partnership-specific Section 707 issue, although reasonable compensation, related-party pricing and assignment of income rules still apply. It has other benefits as well. See our C Corporation as Mothership section for more information.
WCG CPAs & Advisors also offers a Multi-Entity Quick Launch tax strategy session (wcginc.com/strategy) to go over all this gibberish and apply it to your specific objectives.
Jason Watson, CPA, is a Partner and the CEO of WCG CPAs & Advisors, a boutique yet progressive tax, accounting and business consultation firm headquartered in Colorado Springs, Colorado. With 7 partners and 110 incredible professionals across offices in Colorado, South Dakota, Wyoming and India, WCG serves small business owners, real estate investors and taxpayers worldwide.
Taxpayer’s Comprehensive Guide to LLCs and S Corps 2025 Edition
 This KB article is an excerpt from our 420+ page book (some picture pages, but no scatch and sniff) which is available in paperback from Amazon, as an eBook for Kindle and as a PDF from ClickBank. We used to publish with iTunes and Nook, but keeping up with two different formats was brutal. You can cruise through these KB articles online, click on the fancy buttons below or visit our webpage which provides more information.
2027 EDITION IS CURRENTLY BEING WORKED (partial releases throughout November)
 |
 |
 |
| $49.95 | $39.95 | $29.95 |
Chat With a Tax Pro
Taxes can be tricky. Chat with a WCG human now and get questions answered.