
Real Estate Holding Company and Operating Company
Table Of Contents
Should your business own its building? It is one of the most common situations where you own two entities that conduct business between themselves. For example, you are a typical poor accounting firm with the usual high maintenance clients, and you feel that everything would be better if you also owned your own office building. You would create an LLC as the real estate holding company which owns the building, and another LLC (probably taxed as an S Corp) for the operating company. Keep the building out of the S Corp itself, since appreciated real estate is hard to get back out of an S Corp without a taxable event (more on trapped assets in Chapter 4).
This allows for some excellent ownership separation. For example, if you and your father-in-law own the building, he doesn’t have a stake in your accounting firm, and vice versa (didn’t we just scare you with this idea, and now we are bringing it up as an example… we’re evil). You might also want to make one of your key employees a business partner in your operations, but they should not have a stake in the building. Think of it as a firewall between the two, and a much less awkward Thanksgiving.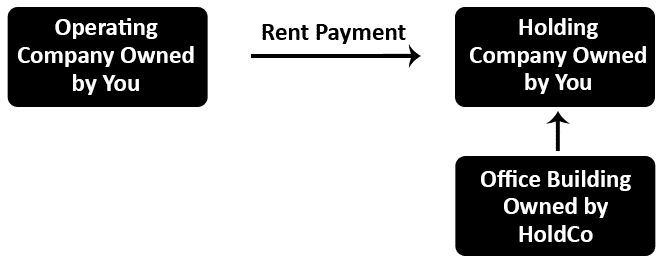
Please keep in mind that rental properties, including self-rentals, are mostly wealth-building strategies and not tax reduction strategies. Yes, depreciation and cost segregation (with 100% bonus depreciation now permanent with OBBBA) can yield some accelerated tax savings, but even that is primarily a wealth-building move. And with a self-rental, there is a catch, which we get to in a moment.
The real estate holding company and operating company arrangement can also reduce self-employment taxes since this conduit changes the color of money. Huh? If your operating company is a sole proprietorship or a partnership, its profit gets hit with self-employment tax and income tax. Rent paid to the real estate holding company reduces that profit, and the rental income on the other end is not subject to self-employment tax (IRC Section 1402(a)(1)).
In an S Corp, most of that savings disappears, since the profit left after your reasonable salary was never subject to payroll taxes in the first place. Rent reduces the S Corp’s pass-through profits, not the payroll taxes on your salary, and the same income simply shows up on the rental side. You are moving taxable income between entities, not making it disappear.
Here is the part that does help S Corp owners. Rent is normally passive income, but rent from a business you materially participate in is recharacterized as nonpassive under the self-rental rule (Treas. Reg. 1.469-2(f)(6)). The upside is that self-rental income escapes the 3.8% net investment income tax, because the regulations treat it as earned in the ordinary course of a trade or business (Treas. Reg. 1.1411-4(g)(6)).
Why does the rule exist? To stop a clever move. Say you own other rentals throwing off passive losses you can’t use. Without the self-rental rule, you could have your operating company pay your real estate holding company a big fat rent check, manufacture passive income, and soak up those losses. The IRS saw that coming. Like a mile away. Self-rental profit is nonpassive, so it cannot absorb passive losses from your other rentals. And it only works in one direction-
- Self-rental profit is nonpassive. It cannot offset passive losses from your other rentals.
- Self-rental losses stay passive. They cannot offset your operating income or other nonpassive income.
Here is another wrinkle. The self-rental rule applies to each owner separately. Remember your father-in-law who owns part of the building but has nothing to do with your accounting firm? His rental income can remain passive, while your share is nonpassive because you materially participate in the business. Same building, same rent check, different tax treatment. Isn’t that special?
Heads the IRS wins, tails you lose. This bites hardest with cost segregation and bonus depreciation, which can turn a profitable self-rental into a loss that, unless you have other passive income to absorb it, just sits there on Form 8582 and gets carried forward until you sell the building (or have profit within the rental activity).
The fix is sometimes grouping the rental and the operating business into one activity, provided they form an appropriate economic unit. Under Treas. Reg. 1.469-4(d)(1), grouping is available when-
- The rental is insubstantial compared to the business, or
- The business is insubstantial compared to the rental, or
- Each owner of the operating business holds the same proportionate ownership interest in the rental.
A married couple filing jointly counts as one owner here, so one spouse can own the business and the other the building. You still must materially participate in the combined activity, the grouping must be disclosed on your tax return (Rev. Proc. 2010-13), and once made it generally sticks. Our rental book, I Just Got a Rental, What Do I Do?, walks through grouping elections in detail.
And here is the irony. The ownership separation we celebrated earlier, with your father-in-law in the building and your key employee in the business, can knock out the matching ownership test. Unless one activity is insubstantial next to the other, grouping is off the table. You sometimes must choose between flexible ownership and favorable passive loss treatment. You don’t always get both.
Sidebar: Renting to your own accounting firm, law firm or medical practice? Watch the Section 199A deduction. When there is 50% or more common ownership between a rental business and a specified service trade or business (SSTB), the rental activity serving that business is also treated as an SSTB for Section 199A purposes (Treas. Reg. 1.199A-5(c)(2)). Above the applicable income thresholds and phaseout range, you get no deduction on that rental income either. Nice try, though.
Beauty! At WCG, self-rentals come with three non-negotiables-
- A written lease.
- Rent at market rates.
- Rent that actually gets paid, not just accrued on the books.
An independent rent appraisal is an excellent way to document fair-market rates, especially when the operating company has owners who do not share in the building’s ownership. Rent that is too high or too low between related entities invites the IRS to reallocate it (IRC Section 482). The rent appraisal is also a good idea in the expansion of ownership. For example, Jason and Tina Watson own the building that WCG CPAs & Advisors leases. As WCG has expanded ownership to other partners, the rent payment to Jason and Tina needs to be above reproach; ergo, a rent appraisal. This reduces office politics and hurt feelings. Maybe just office politics.
Jason Watson, CPA, is a Partner and the CEO of WCG CPAs & Advisors, a boutique yet progressive tax, accounting and business consultation firm headquartered in Colorado Springs, Colorado. With 7 partners and 110 incredible professionals across offices in Colorado, South Dakota, Wyoming and India, WCG serves small business owners, real estate investors and taxpayers worldwide.
Taxpayer’s Comprehensive Guide to LLCs and S Corps 2025 Edition
 This KB article is an excerpt from our 420+ page book (some picture pages, but no scatch and sniff) which is available in paperback from Amazon, as an eBook for Kindle and as a PDF from ClickBank. We used to publish with iTunes and Nook, but keeping up with two different formats was brutal. You can cruise through these KB articles online, click on the fancy buttons below or visit our webpage which provides more information.
2027 EDITION IS CURRENTLY BEING WORKED (partial releases throughout November)
 |
 |
 |
| $49.95 | $39.95 | $29.95 |
Chat With a Tax Pro
Taxes can be tricky. Chat with a WCG human now and get questions answered.